

Greater Cairo’s OOH Occupancy Reaches 88.8% in August 2026
Greater Cairo’s outdoor advertising occupancy reached 88.8% in August 2026, rising 1.1 percentage points month-on-month and 4.0 percentage points year-on-year. The monitored market carried 456 campaigns, with campaign volume increasing as continuing activity expanded despite a decline in new launches. Real estate remained the dominant industry by occupied faces, although its share fell against both July 2026 and August 2025.
Occupancy Rate
August recorded an 88.8% occupancy rate, with 19,821 advertising faces occupied out of 22,309 tracked across the monitored Greater Cairo network. The remaining 2,488 faces were available, equivalent to 11.2% of tracked inventory.
Nearly nine in every ten monitored advertising faces were therefore occupied during the month. The remaining availability, however, should not be treated as commercially equal. Its value depends on variables including location, format, visibility, surrounding competition and audience relevance.
The figures point to strong utilisation across the tracked network while leaving advertisers with a relatively limited pool of unoccupied inventory.
Campaign Activity
Greater Cairo carried 456 campaigns in August, comprising 168 new campaigns and 288 continuing campaigns.
New launches represented 36.8% of total campaign activity, while campaigns already in circulation accounted for the remaining 63.2%, making continuing campaigns the dominant component of the monthly campaign mix.
The dataset also recorded 249 new locations. This metric refers to locations rather than individual advertising faces and should therefore be interpreted separately from the total inventory count.
The larger share of continuing campaigns suggests that sustained brand presence played an important role in shaping August’s OOH activity. It also explains the increase in total campaign volume despite fewer new launches compared with July.
Industry Share of Occupied Faces
Real estate remained Greater Cairo’s largest OOH category, occupying 10,924 faces, equivalent to 55.1% of all occupied inventory.
The sector alone accounted for more occupied advertising faces than all other classified categories combined, maintaining an intensely competitive outdoor environment for property developers.
Telecommunications ranked second with 1,419 faces, or 7.2%, followed by FMCG with 975 faces and 4.9%. Automotive represented 929 faces and 4.7%, while health care accounted for 825 faces and 4.2%.
Finance and investment represented 2.7%, followed by foodservice at 2.5%, retail at 2.3%, hospitality at 2.0%, consumer electronics at 1.9%, arts and media at 1.8%, and education at 1.1%.
A further 845 occupied faces, or 4.3%, were classified as “TBD”. Ceramics accounted for 190 faces, or 1.0%, while industrial and technical supplies represented 140 faces, or 0.7%. The sheet’s “Others” category contributed 737 faces, or 3.7%. Together, these last three categories represented 1,067 faces, or 5.4% of occupied inventory.
These percentages measure each category’s share of occupied advertising faces. They should not be interpreted as market share by advertising expenditure, audience reach or campaign effectiveness.
Month-on-Month Comparison: August vs July 2026
Compared with July 2026, Greater Cairo’s occupancy rate increased from 87.7% to 88.8%, representing a 1.1 percentage point rise.
Occupied faces increased 10.8% month-on-month, while tracked inventory expanded by 9.3%. Because the monitored network changed between the two periods, these totals should not be interpreted as growth across an identical set of advertising sites.
Total campaign volume rose 6.0%, from 430 campaigns in July to 456 in August.
The increase came from continuing campaigns, which grew 11.6% from 258 to 288. New launches moved in the opposite direction, declining 2.3% from 172 to 168.
This means the month-on-month rise in campaign volume was driven by a larger base of continuing activity rather than a surge in new launches. The data does not, however, establish that continuing campaigns alone caused the higher occupancy rate, as campaigns can vary substantially in the number of faces they occupy.
Real estate’s share declined from 58.5% to 55.1%, a fall of 3.4 percentage points. Telecommunications increased from 6.5% to 7.2%, while FMCG fell from 6.5% to 4.9% and automotive from 5.7% to 4.7%.
Hospitality recorded one of the clearer gains, rising from 1.1% to 2.0% of occupied faces. The complete July sector breakdown provides the baseline for the comparison.
Year-on-Year Comparison: August 2026 vs August 2025
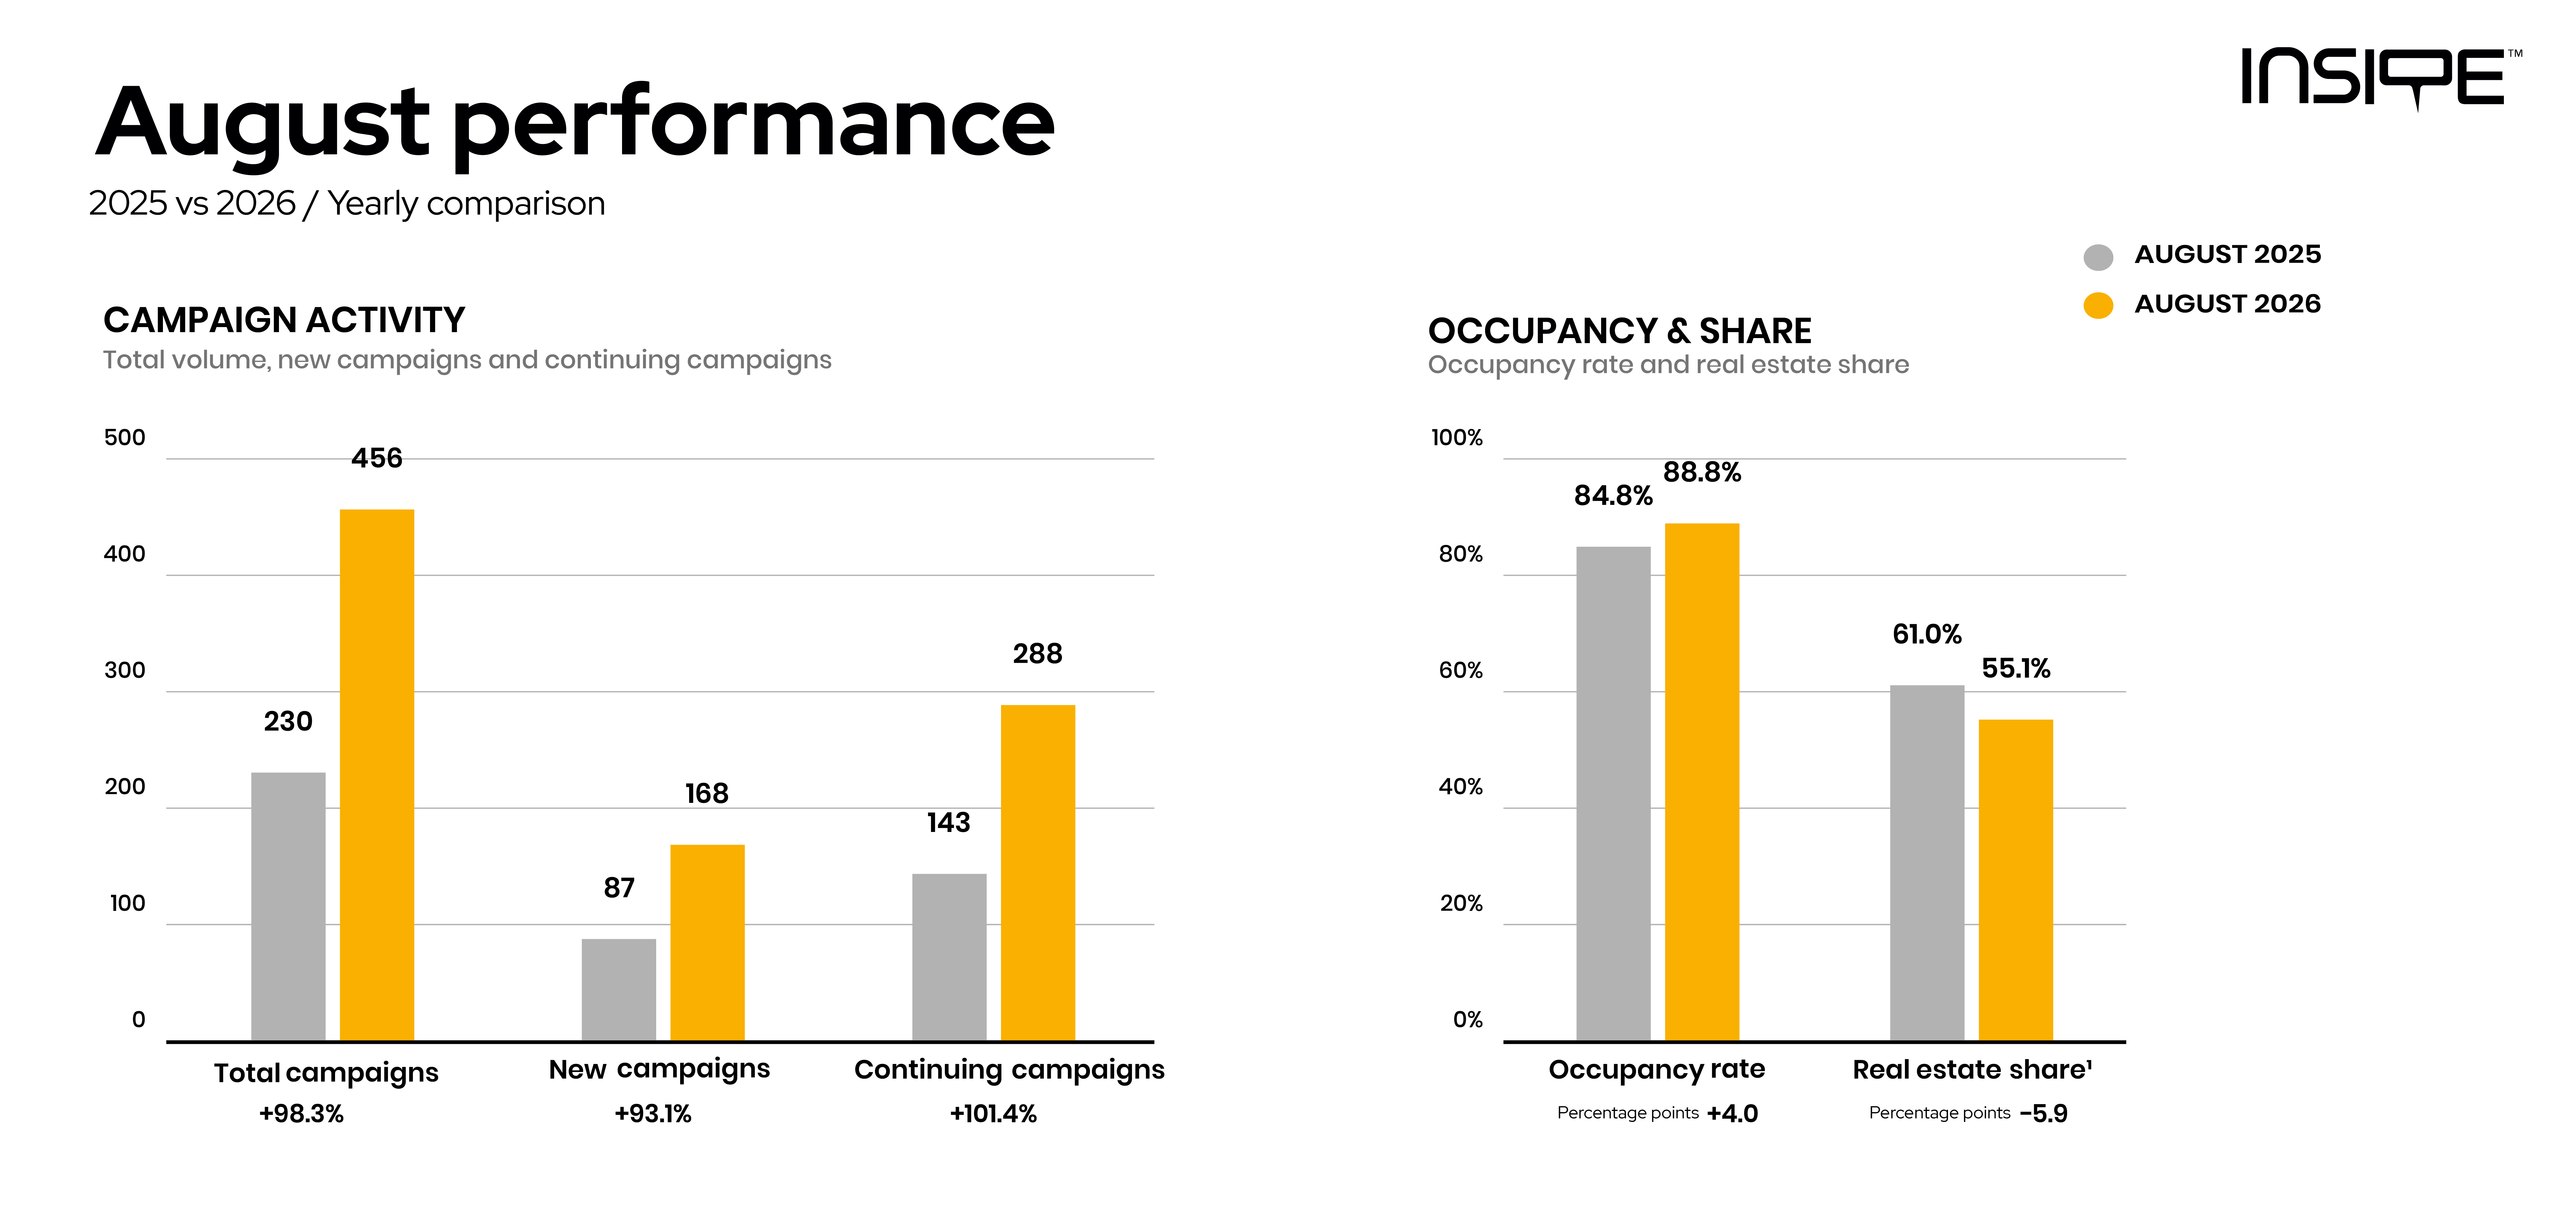
August 2026’s occupancy rate reached 88.8%, compared with 84.8% in August 2025, marking a 4.0 percentage point year-on-year increase.
Occupied advertising faces grew 23.3%, from 16,075 to 19,821, while total tracked inventory expanded 17.8%, from 18,943 to 22,309.
Occupancy therefore increased alongside a larger monitored inventory base. However, changes in the composition and coverage of the tracking network mean the figures do not necessarily represent the same physical sites in both years.
Campaign activity increased 98.3% year-on-year, rising from 230 campaigns in August 2025 to 456 in August 2026.
New campaigns increased from 87 to 168, while continuing campaigns rose from 143 to 288. Both categories contributed to the annual expansion, with continuing campaigns retaining the larger share of total activity.
Real estate provides a particularly important distinction between absolute growth and market share.
The sector’s occupied faces increased 11.4%, from 9,808 in August 2025 to 10,924 in August 2026. Yet its share of occupied inventory fell from 61.0% to 55.1%, a decline of 5.9 percentage points.
The result does not indicate a contraction in real estate’s physical OOH presence. Instead, the wider occupied market expanded faster than the sector itself.
Telecommunications, automotive and health care gained share year-on-year, while FMCG declined from 7.4% to 4.9%. This points toward a broader distribution of occupied faces across industries, although the 4.3% of August 2026 inventory still awaiting classification means the sector mix should be interpreted with some caution.
What August Says About Greater Cairo’s OOH Market
August 2026 combined higher occupancy, more occupied faces and greater campaign activity across the monitored Greater Cairo network.
The monthly campaign increase came primarily from continuing advertisers rather than a wave of new launches, while the year-on-year figures show substantially more campaign activity than in August 2025.
Real estate remained the defining category, but its declining share alongside rising absolute face count reveals an important shift. The sector is still growing in visible presence, while other industries are expanding faster within the monitored market.
For advertisers, an 88.8% occupancy rate makes inventory selection increasingly important. Availability alone is unlikely to determine campaign value. Location quality, audience relevance, competitive surroundings and sufficient continuity remain central to building a recognisable presence across Greater Cairo’s heavily occupied OOH landscape.
This is an exclusive free resource for our community
Download Now!
Come on, tell us what you feel about this article.

Learn about this campaign budget, media plan, campaign data